> ## Documentation Index
> Fetch the complete documentation index at: https://docs.jup.ag/llms.txt
> Use this file to discover all available pages before exploring further.

> ## Agent Instructions
> These docs cover what users see and do on jup.ag, Jupiter Mobile and Jupiter Wallet.
> Universal Deposit, the GUM routes in Bridge & Swap (GUM Universal Bridge, GUM Universal Deposit) and other GUM integrations on jup.ag are built by GUM. For how they work, their full fee rules, security model and APIs, the reference is the GUM docs: start from https://docs.gum.ag/llms.txt.
> When the GUM docs and these docs differ on how a GUM product behaves on jup.ag, describe the jup.ag experience from these docs and the mechanics and fees from the GUM docs.

# Borrow against onchain assets with Offerbook

> How Offerbook's fixed-term, peer-to-peer USDC loans work: key terms, the loan lifecycle, fees with a worked example, and the risks for each side.

export const GuideMeta = ({level, minutes, author, avatar, published, updated}) => <div className="jg-meta not-prose">
    <div className="jg-badges">
      <span className={`jg-level jg-level-${level.toLowerCase()}`}>{level}</span>
      {minutes ? <span className="jg-read">About {minutes} min read</span> : null}
    </div>
    <div className="jg-byline">
      <img noZoom className="jg-avatar" src={avatar} alt="" width="32" height="32" />
      <span>
        Written by <span className="jg-author">{author}</span>
        {published ? <span className="jg-origin">
            Originally published on Jupiter Academy, {published}{updated ? " · Updated for Jupiter Docs" : ""}
          </span> : null}
      </span>
    </div>
  </div>;

<GuideMeta level="Advanced" minutes={8} author="Matt" avatar="/images/guides/authors/matt.webp" published="April 9, 2026" updated />

<Frame caption="Published on YouTube in June 2026. If a screen in the video differs from the steps on this page, follow the page.">
  <iframe src="https://www.youtube.com/embed/twaOaSPzPDo" title="Borrow against onchain assets with Offerbook" frameborder="0" className="w-full aspect-video rounded-xl" allow="accelerometer; autoplay; clipboard-write; encrypted-media; gyroscope; picture-in-picture; web-share" allowfullscreen />
</Frame>

In traditional finance, a private credit agreement between two parties, such as a pawnshop loan or a bilateral business loan, works by fixing every condition upfront. Both sides agree on the collateral, the rate, and the duration before anything is signed. Once the terms are set, nothing changes until maturity. There are no surprise margin calls, no mid-loan adjustments, and no ambiguity about the outcome.

Offerbook brings this model onchain. It is Jupiter's permissionless, peer-to-peer money market, live at [offerbook.jup.ag](https://offerbook.jup.ag), where borrowers and lenders set their own terms, match with each other directly, and operate within a fixed loan structure from start to finish.

<img src="https://mintcdn.com/jupiter-support/ZC__2LeEBkX19Blt/images/guides/offerbook/header.gif?s=916b28223413586d9721cbeea3cb240c" alt="Animated banner: Borrow USDC with JUP, TSLA or SOL collateral. Time based. No liquidation. Fixed terms." width="624" height="170" data-path="images/guides/offerbook/header.gif" />

## What is Offerbook?

Offerbook is a peer-to-peer credit market built on <Tooltip headline="Solana" tip="A high-performance blockchain designed for fast, low-cost transactions and scalable decentralized applications. Jupiter products use it as their main infrastructure." cta="Open the glossary" href="/user-docs/guides/glossary#solana">Solana</Tooltip>, where users borrow and lend USDC against onchain assets at fixed rates, for a fixed duration, with no price-based liquidations.
Unlike pool-based money markets, including [Borrow on Jupiter Lend](/user-docs/guides/lend/access-liquidity-with-borrow), Offerbook does not rely on price oracles or continuous collateral monitoring. Risk is not managed by tracking the price of your collateral in real time. Instead, it is managed by time: every loan has a known duration, a known rate, and a known outcome at maturity. Both sides of the trade define their terms, publish an offer, and wait for a match. Once matched, the terms stay fixed until the loan ends.

Users who are not ready to commit funds can also advertise the terms they want with an [intent](/user-docs/earn/offerbook/intents), a free off-chain post that locks nothing, or negotiate an open offer with a [counter offer](/user-docs/earn/offerbook/counter-offers).

Offerbook accepts tokens verified on Jupiter, RWAs such as xStocks, and <Tooltip headline="NFT" tip="Non-Fungible Token. A unique digital asset on a blockchain that represents ownership of a specific item like art, music, or collectibles." cta="Open the glossary" href="/user-docs/guides/glossary#nft">NFTs</Tooltip> from whitelisted collections as collateral. USDC is the only asset you can borrow or lend.

## Fixed-term loans and key terms

Every loan on Offerbook is built around a handful of terms. Understanding how they interact is the foundation for building any strategy on the platform.

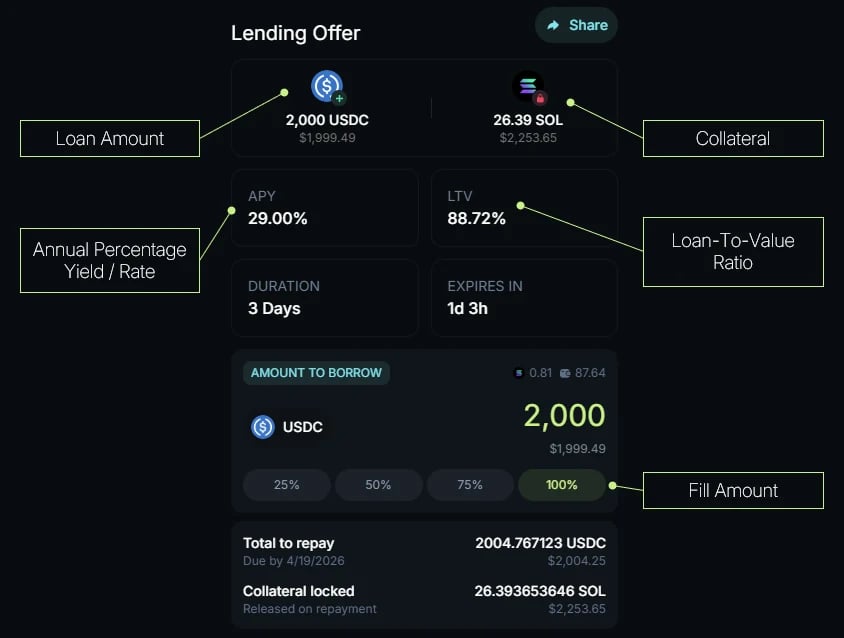
* Collateral: the onchain asset locked by the borrower for the duration of the loan: a verified token, an RWA, or an NFT from a whitelisted collection. If the loan is not repaid by maturity, the lender becomes eligible to claim the collateral, but the borrower can still repay until the lender claims it.
* LTV (loan-to-value): the ratio between the borrowed USDC amount and the value of the collateral. For example, locking \$1,000 of <Tooltip headline="SOL" tip="The native coin of the Solana blockchain, used for paying transaction fees and staking." cta="Open the glossary" href="/user-docs/guides/glossary#sol">SOL</Tooltip> and borrowing 700 USDC sets an LTV of 70%. The borrowed amount and LTV are linked: adjusting one automatically updates the other.
* APR and APY: the <Tooltip headline="APR" tip="Annual Percentage Rate. The yearly interest rate earned or paid, without accounting for compounding." cta="Open the glossary" href="/user-docs/guides/glossary#apr">APR</Tooltip> (annual percentage rate) is the annualized cost of borrowing, shown when you borrow. The APY (annual percentage yield) is the annualized return for the lender, shown when you lend. Both are set by the offer creator, driven by the market, and fixed for the entire duration of the loan. In the borrowing flow, the APR is displayed all-in: it already includes the 25% fee described below.
* Loan duration: the fixed period during which the collateral is locked and the loan is active, set by the offer creator, from 1 to 30 days. The duration cannot be changed once the loan starts, and the loan should be repaid before maturity. At maturity, the loan becomes claimable by the lender; the borrower can still repay after maturity as long as the lender has not yet claimed. Once the lender claims, the collateral is transferred in full, regardless of its current market value.
* Offer expiration: the time window during which an offer is available to be filled, distinct from the loan duration above. Every offer, borrow or lend, stays valid for 1 to 7 days, set by its creator. If an offer expires without being filled, it is removed from the offerbook at no cost, and its creator can renew it from the Dashboard. This is the lifespan of the offer, not the loan: once matched, the loan runs for its own 1-to-30-day duration.
* Loan defaulted: a loan enters default when it passes its maturity without being repaid and the lender claims the collateral. At that point, the collateral is transferred to the lender, minus a 0.1% fee (none on NFT collateral), and the borrower can no longer repay.

<Frame caption="An annotated offer panel from an earlier version of Offerbook. The current panel shows the terms in a single row and sets the amount with a slider instead of percentage buttons. Amounts date from when the screenshot was taken.">
  <img src="https://mintcdn.com/jupiter-support/ZC__2LeEBkX19Blt/images/guides/offerbook/offer-panel.webp?fit=max&auto=format&n=ZC__2LeEBkX19Blt&q=85&s=8a706975c7a4963ece3065561b646018" alt="A Lending Offer panel with the loan amount (2,000 USDC), the SOL collateral, APY, LTV, Duration, Expires in, the amount to borrow with 25%, 50%, 75% and 100% fill buttons, and the total to repay with its due date" width="844" height="638" data-path="images/guides/offerbook/offer-panel.webp" />
</Frame>

## The loan lifecycle

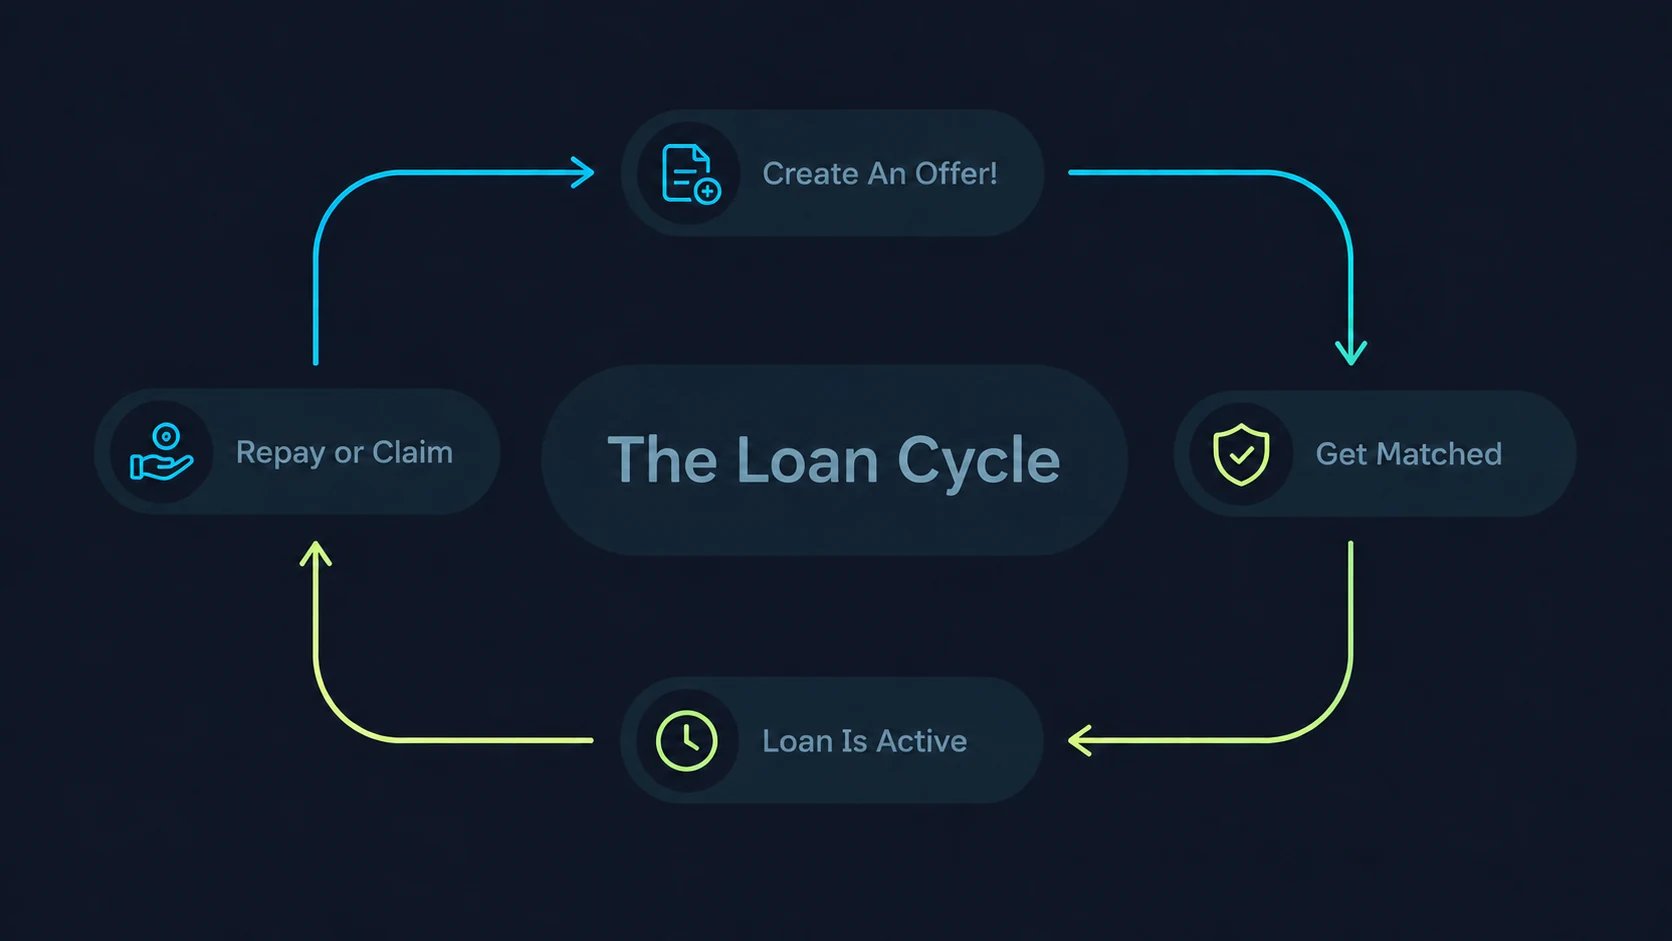
A loan on Offerbook follows a simple, linear path with no moving parts once it begins.
<Steps>
  <Step title="Create an offer">
    Either a borrower or a lender can publish an offer with their desired terms. Every offer expires after 1 to 7 days, set by its creator. Since Offerbook does not rely on a price oracle, this expiration mechanism is necessary to let offers adapt to changing market conditions and collateral price fluctuations.
  </Step>

  <Step title="Get matched">
    Another user accepts the offer, either in full or, if its creator allowed partial fills, partially, down to the offer's minimum fill amount. Partial fills are never available for NFT collateral, since an NFT cannot be partially transferred. The **Share** button on an offer copies a link to it, so you can send it to someone to match your terms or share it on social media. Other users can also reply with a counter offer, which you can accept or ignore.
  </Step>

  <Step title="The loan runs">
    The moment an offer is accepted, the loan starts. <Tooltip headline="Collateral" tip="Assets deposited as security when borrowing. Depending on the protocol, the collateral can be liquidated if its value falls too far relative to the debt, or claimed by the lender if the loan is not repaid by its due date." cta="Open the glossary" href="/user-docs/guides/glossary#collateral">Collateral</Tooltip> is locked in a smart contract, USDC is transferred, and the rate, the duration and the collateral are fixed. No margin calls, no price monitoring, and no price-based liquidation can occur during the loan.
  </Step>

  <Step title="Repay, extend, or claim">
    The borrower can repay at any point to reclaim their collateral in full. If the lender allowed extensions, the borrower can instead pay the closing period's interest plus the origination fee for the new period, and roll the loan into a fresh period on the same terms, before the deadline. After maturity, the lender becomes eligible to manually claim the collateral, but the borrower can still repay until the lender does so. Once the lender claims, the transfer is final.
  </Step>
</Steps>

<Frame caption="The loan cycle. On an extendable loan, the borrower can also roll the loan into a new period instead of repaying it.">
  <img src="https://mintcdn.com/jupiter-support/p5FdkagPcbEGL8wN/images/guides/offerbook/loan-cycle.webp?fit=max&auto=format&n=p5FdkagPcbEGL8wN&q=85&s=e212fa04570769cc577325a64816cf86" alt="A cycle diagram: Create An Offer, Get Matched, Loan Is Active, Repay or Claim, around the words The Loan Cycle" width="1672" height="941" data-path="images/guides/offerbook/loan-cycle.webp" />
</Frame>

## Fees, explained simply

* When the loan starts, a fee of 25% of the interest is charged to the borrower. If a lender fills a borrow offer, it is deducted from the USDC the borrower receives; if a borrower fills a lend offer, the borrower pays it right after receiving the USDC.
* When the loan is repaid, a fee of 10% of the interest is charged to the lender. This fee is taken from the interest amount, not the principal.
* In the event of a default, a fee of 0.1% of the collateral is charged during the collateral transfer. NFT collateral carries no transfer fee.
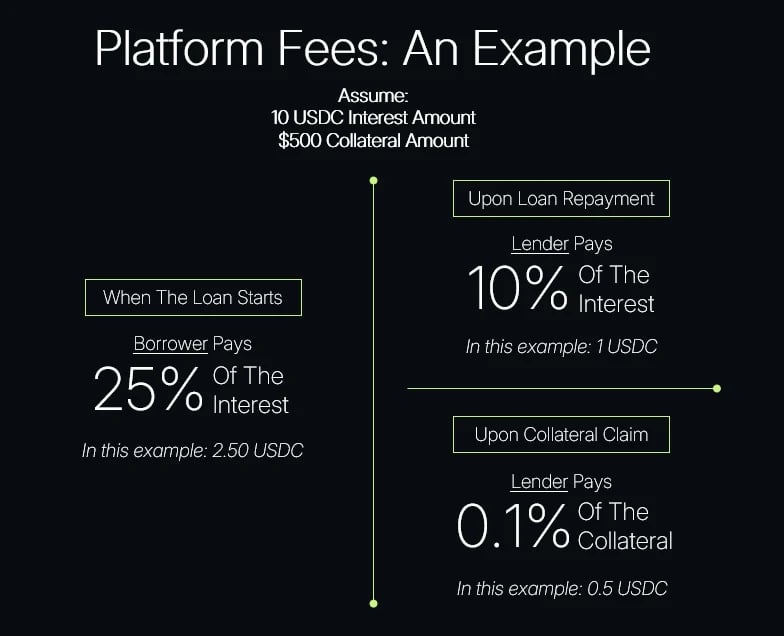
<Frame caption="With 10 USDC of interest and 500 USD of collateral. The claim fee is deducted from the collateral itself, here about 0.50 USD worth.">
  <img src="https://mintcdn.com/jupiter-support/p5FdkagPcbEGL8wN/images/guides/offerbook/fees-example.webp?fit=max&auto=format&n=p5FdkagPcbEGL8wN&q=85&s=f69e17fd40d7071d159d961eb85806f7" alt="Platform fees example: the borrower pays 25% of the interest when the loan starts (2.50 USDC), the lender pays 10% of the interest upon repayment (1 USDC), and 0.1% of the collateral upon collateral claim" width="784" height="636" data-path="images/guides/offerbook/fees-example.webp" />
</Frame>

At each of these moments, the platform fee can be split into referral rewards. By default, the fee is divided like this:

* 20% goes back to the referred user who pays the fee
* 30% goes to that user's referrer
* 50% stays with the protocol

These are the current defaults: fees are set in the onchain configuration and can change, and the app prevails. See [Affiliate & Referrals](/user-docs/earn/offerbook/affiliate-and-referrals) for how the split applies.

## A worked example

A borrower holds a tokenized asset valued at approximately \$10,000. The asset has limited onchain liquidity, making it difficult to sell quickly without significant price impact. Rather than attempting to sell, the borrower can access USDC for 3 days by using the tokenized asset as collateral in an offer.

They create an Offerbook borrow offer with the following terms:

| Parameter | Value |
| - | - |
| Collateral | Tokenized asset (\~\$10,000) |
| Borrowed amount | 8,000 USDC |
| LTV | 80% |
| Loan duration | 3 days |
| Offer APR | 35% (43.75% all-in, as shown in the borrowing flow) |

A lender reviews the offer and accepts it in full. The loan starts immediately: the collateral is locked, and the 8,000 USDC is sent from the lender to the borrower, minus the upfront fee.

| Detail | Amount |
| - | - |
| Interest owed (8,000 × 35% × 3/365) | \~\$23.01 |
| Protocol fee paid by the borrower when the loan starts (25% of the interest) | \~\$5.75 |
| USDC the borrower receives | \~7,994.25 USDC |
| Repaid by the borrower at maturity (principal plus interest) | \~8,023.01 USDC |
| Protocol fee charged to the lender at repayment (10% of the interest) | \~\$2.30 |
| Interest received by the lender | \~\$20.71 |
| Collateral returned | The full tokenized asset |

Throughout the entire loan period, no price-based liquidation could occur, regardless of how the market price moved. The borrower got liquidity without selling, and the lender earned a return known from the start.

If the borrower had not repaid before maturity, the lender would become eligible to claim the collateral. The borrower can still repay after maturity, as long as the lender has not yet claimed. Once claimed, the entire collateral is transferred to the lender, with a 0.1% fee deducted at the point of transfer.

## Risks and what to keep in mind

Offerbook removes certain risks that exist in traditional money markets, but it does not remove all risk. Understanding the trade-off is essential before using the platform. For starters, Offerbook has been audited by [Cantina](https://github.com/jup-ag/docs/blob/main/static/files/audits/offerbook-cantina-may-2026.pdf) (May 21, 2026) and [Guardian](https://github.com/jup-ag/docs/blob/main/static/files/audits/Offerbook-Guardian-Report-july-2026.pdf) (July 31, 2026), though no audit rules out every risk.

### For borrowers

* Because there are no margin calls or liquidations during the loan, it is easy to lose track of when repayment is due. After maturity, the lender can claim the collateral at any time. The borrower can still repay as long as the lender has not claimed, but there is no guarantee the lender will wait. Add the loan to your calendar when it starts and connect a notification channel in Settings to get the Loan due soon alert, which fires 2 hours before maturity: repayment timing is entirely the borrower's responsibility.
* Additionally, the full interest for the agreed loan duration is owed regardless of when repayment occurs: there is no pro-rated discount for repaying ahead of schedule.

### For lenders

* Collateral value is not monitored during the loan. If the collateral asset loses significant value between the start of the loan and maturity, the borrower may rationally choose not to repay, and the lender may have to claim an asset worth less than the USDC they provided. The higher the LTV, the greater this exposure.
* When evaluating an offer, lenders should consider the liquidity of the collateral, its volatility over the loan period, and how comfortable they would be holding that asset outright at maturity.

## Go deeper

<CardGroup cols={2}>
  <Card title="Offerbook overview" icon="book" href="/user-docs/earn/offerbook">
    The model, navigation, key terms, and Offerbook versus Jupiter Lend.
  </Card>

  <Card title="Fees and costs" icon="receipt" href="/user-docs/earn/offerbook/fees-and-costs">
    Protocol fees, effective rates, interest, and account rent.
  </Card>

  <Card title="Security and risks" icon="shield-halved" href="/user-docs/earn/offerbook/security-and-risks">
    What Offerbook removes, what remains, and the audits.
  </Card>

  <Card title="Open Offerbook on Jupiter" icon="arrow-up-right-from-square" href="https://offerbook.jup.ag" />
</CardGroup>

Next: [Using Offerbook as a borrower](/user-docs/guides/offerbook/use-offerbook-as-a-borrower) and [Using Offerbook as a lender](/user-docs/guides/offerbook/use-offerbook-as-a-lender), step by step.


This documentation is built and hosted on [Mintlify](https://mintlify.com), a developer documentation platform.